 admin
Between cash reserves and short-term paper on corporate balance sheets, a controversial new asset has taken root: bitcoin.
The corporate treasury traditionally dedicated to liquidity management and risk aversion has turned into an active battleground for capital allocation strategy. While absolute holdings remain modest next to cash reserves of global conglomerates, adoption by early corporate movers has forced boards to confront fundamental questions about treasury mandates.
The Strategic Argument for Holding Bitcoin
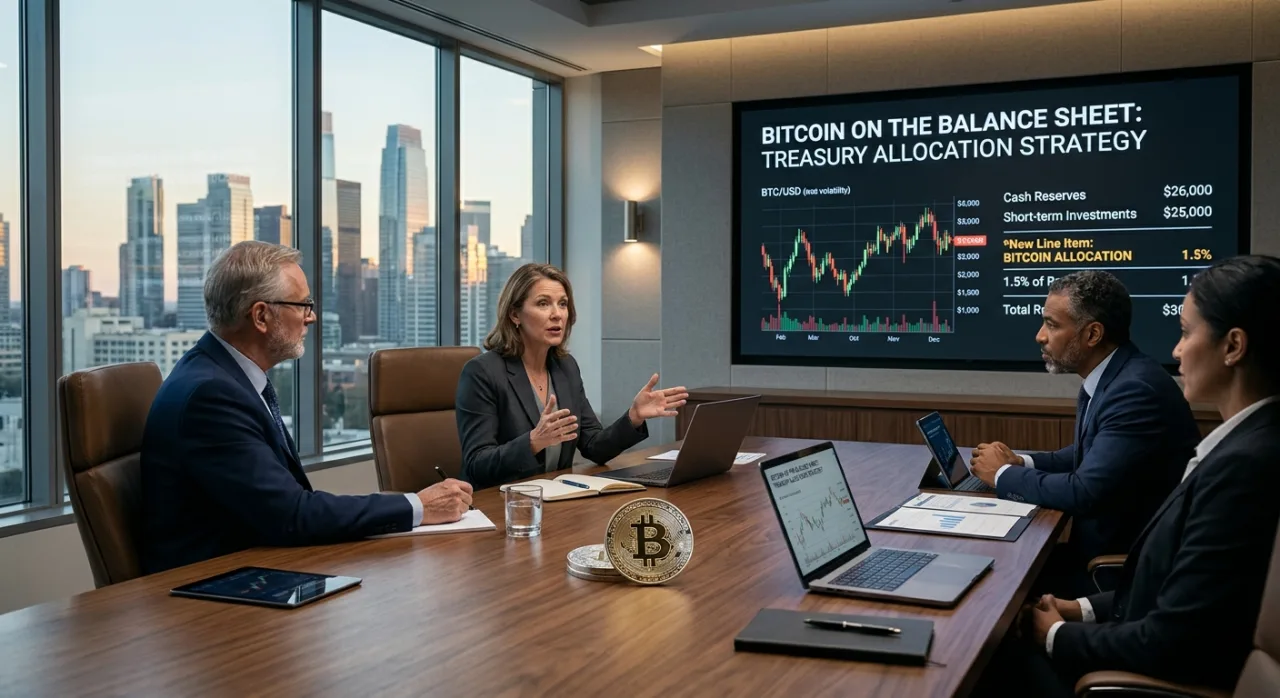
Proponents frame bitcoin as a modern reserve asset designed to hedge against systemic fiat currency degradation:
-
Inflation Protection: Holding excess cash for multi-year periods subjects balance sheets to real purchasing power loss when yields lag inflation. Bitcoin’s fixed supply schedule provides a scarce digital reserve asset.
-
Brand & Tech Signalling: Allocating a small percentage of corporate reserves signals technological forward-thinking to customers, tech talent, and shareholders.
-
Operational Alignment: For firms operating in fintech or digital assets, digital asset holdings serve as a direct balance sheet hedge.
-
Disciplined Governance: Treasury allocations undergo formal board authorization, capped sizing, and structured disclosures similar to managing foreign currency exposure.
Primary Governance & Risk Objections
Opponents focus on volatility, financial accounting hurdles, and core corporate fiduciary duties:
-
Extreme Price Volatility: Sharp asset drawdowns undermine a treasury’s primary mandate to ensure predictable liquidity for payroll, debt service, and operating capital.
-
Administrative Complexity: Despite improved fair-value accounting frameworks, digital assets still introduce custody risk, audit overhead, and distinct tax liabilities.
-
Scope Creep & Mandate Integrity: Shareholders seek operating performance from corporations, not unhedged crypto bets. Excessive exposure risks turning operating businesses into leveraged cryptocurrency holding vehicles.
Framework: Prudent Adopters vs. Speculative Programs
| Treasury Strategy Dimension | Prudent Corporate Framework | Speculative Corporate Approach |
| Capital Source |
Funded purely from surplus operational cash flows |
Funded through debt issuance or equity dilution |
| Allocation Limits |
Strict percentage caps on total treasury reserves |
Variable, market-chasing purchasing targets |
| Custody & Security |
Institutional-grade multi-signature storage |
Fragmented or self-custody setups |
| Governance Policy |
Written execution and rebalancing rules |
Discretionary buying based on market sentiment |